Brent Crude Oil Forward CurveBrent Crude Oil Forward Curve
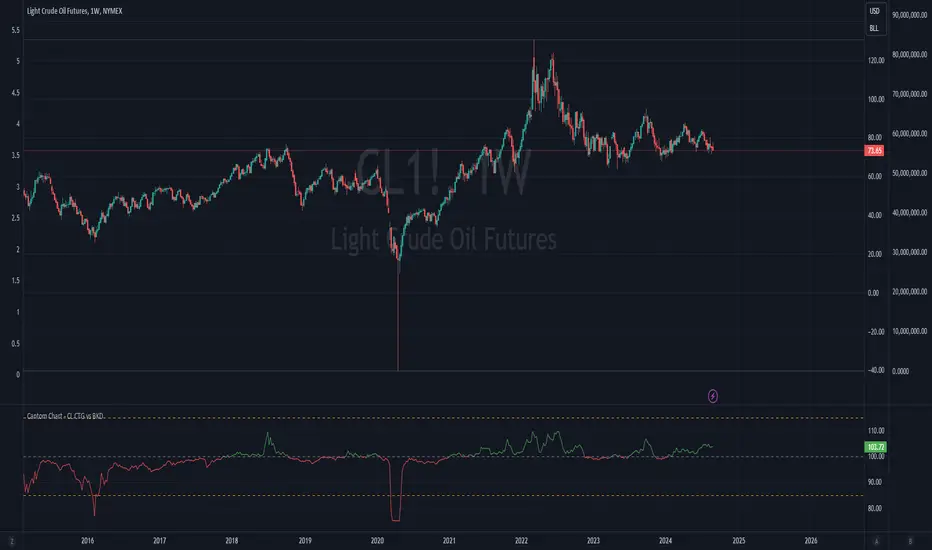
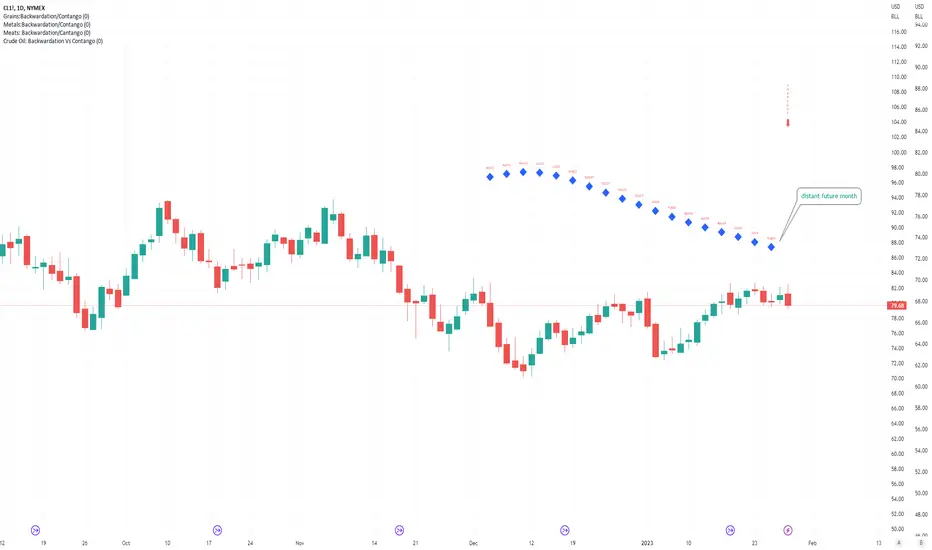
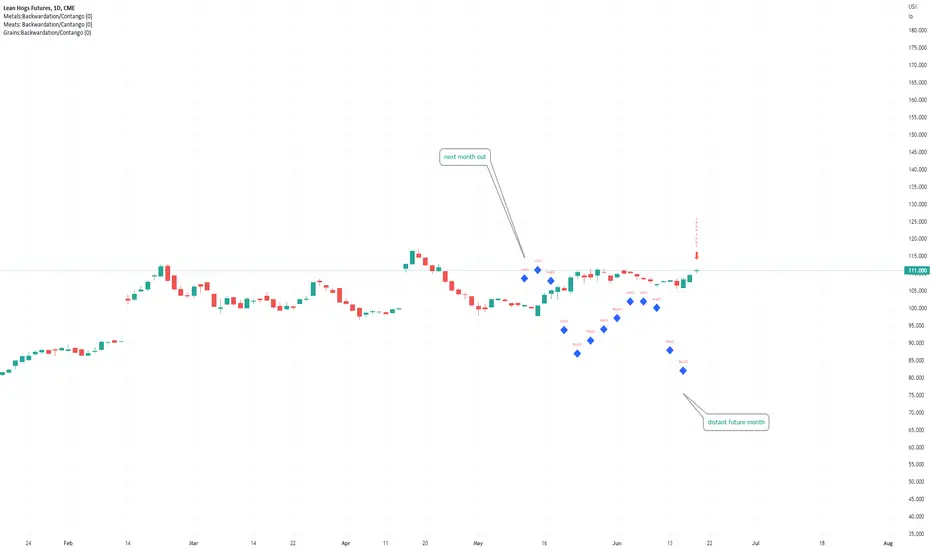
The Brent Crude Oil Forward Curve is a market-structure visualization tool designed to display the relationship between consecutive Brent crude oil futures contracts across a 12-month horizon.
The indicator builds a forward curve from twelve consecutive Brent futures contracts and presents their prices both graphically and in a structured data table. This allows users to observe the shape, slope and evolution of the Brent term structure directly alongside the underlying market.
CURVE STRUCTURE
The indicator automatically identifies the prevailing structure of the displayed curve:
BACKWARDATION — when deferred futures contracts trade below the front contract.
CONTANGO — when deferred futures contracts trade above the front contract.
The curve is displayed dynamically, allowing changes in the term structure to be identified visually rather than by examining individual futures contracts separately.
12-CONTRACT FORWARD CURVE
Twelve consecutive Brent futures contracts are displayed. Each point on the curve includes the contract month, price and spread relative to the front contract.
The accompanying table provides:
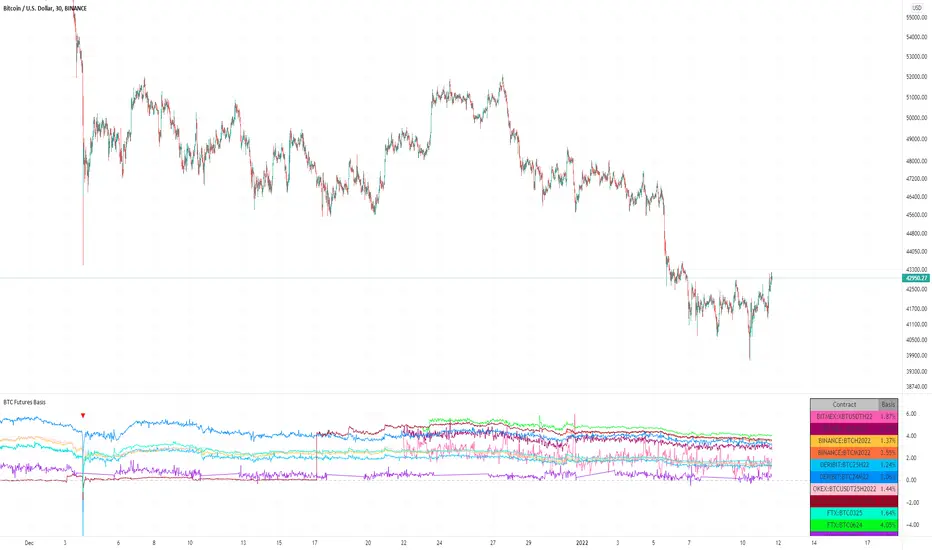
• Contract symbol
• Contract month
• Futures price
• Spread versus the front contract
The summary row shows the current curve structure, the front-to-last contract range and the total spread across the displayed 12-month curve.
AUTO ROLL
The indicator includes a calendar-based auto-roll mechanism that automatically advances the displayed 12-contract sequence as the calendar progresses. By default, the sequence begins two calendar months ahead of the current month. The contract sequence is generated dynamically, eliminating the need to manually replace each futures symbol every month. A Manual Front Month Offset is also available for users who wish to inspect an adjacent contract sequence or manually shift the starting point of the curve.
PRICE TIMEFRAME
By default, contract prices follow the chart timeframe. Users may select a different Price Timeframe when they want the forward curve calculations to reference another timeframe independently of the underlying chart.
DISPLAY CONTROLS
The Inputs menu provides independent controls for displaying or hiding the data table, individual contract labels and branding panel. Point spacing, horizontal positioning and label distance can also be adjusted to accommodate different screen sizes and chart layouts.
DESIGN AND METHODOLOGY
This script combines automated Brent contract sequencing, calendar-based contract management, 12-contract term-structure construction, spread calculations relative to the front contract, dynamic curve visualization and synchronized tabular presentation within a single analytical framework.
Rather than analyzing individual futures contracts separately, the script transforms the prices of twelve consecutive Brent futures contracts into a synchronized representation of the term structure. The graphical curve, contract labels, spreads, market-structure classification and contract table are updated together as the futures sequence evolves. The implementation and presentation logic were developed specifically for this script.
INTERPRETATION
The indicator is intended to help users study the term structure of Brent crude oil futures. Changes in the shape and slope of the forward curve can provide useful information about how the futures market is pricing near-term versus deferred delivery.
Forward-curve structure should not be interpreted in isolation as a directional trading signal. It is one component of broader crude-oil market analysis and should be evaluated together with price action, fundamentals, positioning, inventories and other relevant market information. อินดิเคเตอร์

VIX Curve Pro - Real-Time Term Structure with StatisticsThis indicator displays the VIX term structure as a spatial curve directly on the chart, allowing you to instantly identify whether the volatility market is in contango or backwardation.
It shows the relationship between different VIX maturities (9D, 30D, 3M, 6M, 1Y) as a single curve.
It also shows some statistics and helps with market detection:
Historical percentile rankings for key VIX ratios
Real-time min/max/average/median values over lookback period
Current VIX term values with regime indicators
Understand where current conditions sit relative to historical context
Automatic identification of contango vs backwardation states
Visual indicators showing which part of the curve is inverted
Optional information guide explaining market states and trading implications
How to Use:
The curve shows the "shape" of volatility expectations across time. An upward-sloping curve (contango) means calm markets where longer-term volatility is priced higher than near-term. A downward-sloping curve (backwardation) shows market stress, where near-term volatility spikes above longer-term expectations.
Use the statistical tables to understand whether current ratios are at historical extremes (high percentile rank) or lows (low percentile rank), helping you gauge whether volatility structures are stretched or compressed.
Perfect for:
Volatility traders and options strategists
VIX futures and options traders
Understanding market fear and complacency levels
Timing volatility trades based on term structure
In the example above, I've added a chart with TVC:VIX , CBOE:VIX9D , CBOE:VIX3M and $CBOE:VIX6M. It is possible to see that although they are still in backwardation (short term vix is lower than long term), it might be close to flip. This kind of situation deserve extra attention. You can set alerts to when it flips.
This is a simple but useful indicator. Let me know if you have any questions! อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

Celestial Pair Spread Hello friends, after a very long time!
Today, I tried to put into code an idea that came to my mind spontaneously and suddenly.
Note :
This script is experimental and improvable.
I haven't had a chance to try it yet.
TIMEFRAME : 1D (Daily Bars)
CELESTIAL SPREAD
The spread moves in a very limited area and is consistent within itself, especially on days far from the end of the contract.
That's why there is a reassuring sky atmosphere. That's why this name was given completely improvised.
Basic logic of the script
We enter the name of the CME Futures contract we want to enter:
Ex : CL1! , ES1! , ZC1! , NQ1!
The script creates us a pair trade parity divided into secondary contracts.
Example : ES1!/ES2!
What is pair trading?
I will explain briefly here.
For users who are wondering:
www.investopedia.com
Let's get back to our topic.
Now we have created a parity that does not actually exist.
This parity is the manifestation of the relative movements of two contracts.
When the parity rises, ES1! increased,ES2! has fallen.
In the opposite case, We can say: ES1! Contract has been dropped ES2! has increased.
Pair trading is generally a trade that needs to be kept in mind from time to time.
It is a method preferred by professionals who can process very quickly.
Market risk is minimal, but since 2 contracts are purchased, more money is paid and very low percentage profits are made.
It is very expensive to do pair trading, especially with oil and its derivatives and interest security derivatives.
The contract we are considering has micros. (small-item contracts tied to the same value)
So when we switch to our broker MES1!/MES2! We will trade.
For all CME futures :
www.cmegroup.com
Anyway, let's continue:
The script created the parity showing its relationship with the next contract and plotted it as bars.
Celestial bands are just like Bollinger bands, but they consist of 3 bands based on percentage changes rather than standard deviation.
The middle band is obtained from moving averages.
The upper and lower bands are the middle band subjected to a threshold value.
The threshold value can be changed.
0.15 percent was charged for this script.
CAUTION :
As can be seen in the example below;
The most important thing is not to make any transactions when the contract switch dates are approaching.
Therefore, it is recommended to use it just below the main chart.
The blue bars in the parity are
Values that outside the upper and lower threshold values are colored blue.
For this condition
Alerts has been added.
Don't forget to add alert and edit.
MAIN PURPOSE
It is aimed to start a pair trade when such conditions come and to quickly close the trades when the parity basis reaches the value.
OTHER IMPORTANT POINTS
Other issues are broker related issues.
Difference between initial margins and maintanence margins of contracts (between 1! and 2!)
It shouldn't be too high.
The commission should not be too high.
Leverage must be high because the profit percentage is very low.
To calculate leverage you must divide your contract size by the relevant margin requirement.
Sample margin requirement table:
www.interactivebrokers.com
RISKS
It is an experimental and intellectual script,
the risk of contract price differences (maybe it will not leave a profit except for very extreme values)
I remind you of the quickness risk that comes from a two-legged trade.
Alerts definitely synchronized with an audible alert sent to a smartphone as an e-mail notification and displayed on the locked screen for quick action.
Best regards! อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

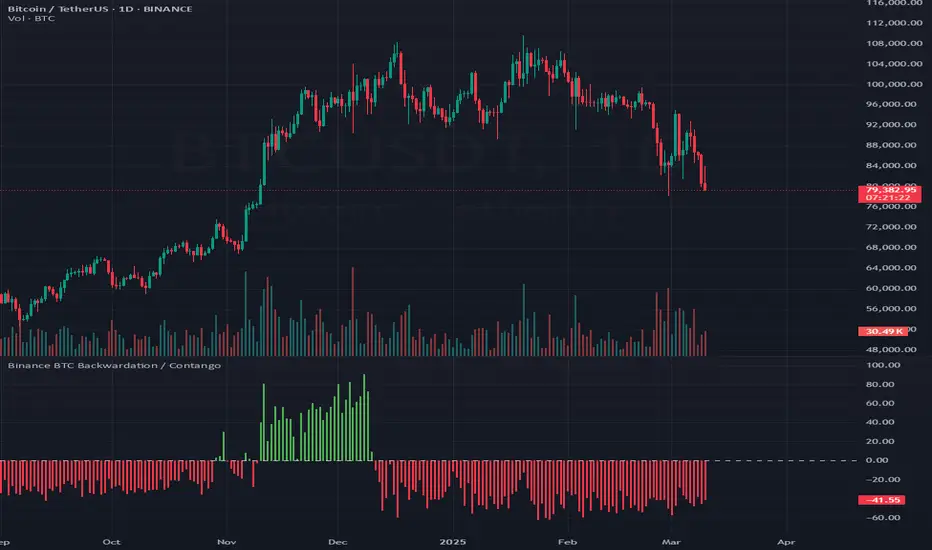
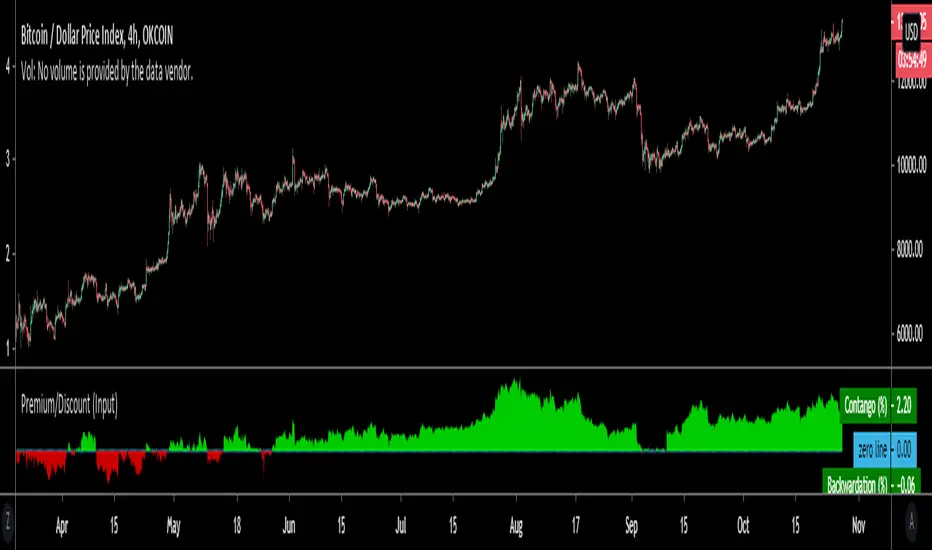
BTC Volume Contango IndexBased on my previous script "BTC Contango Index" which was inspired by a Twitter post by Byzantine General:
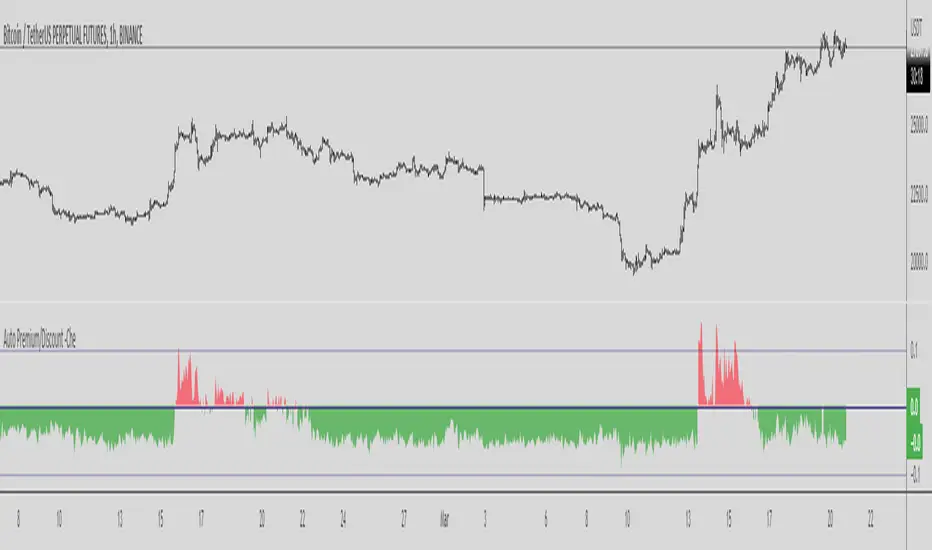
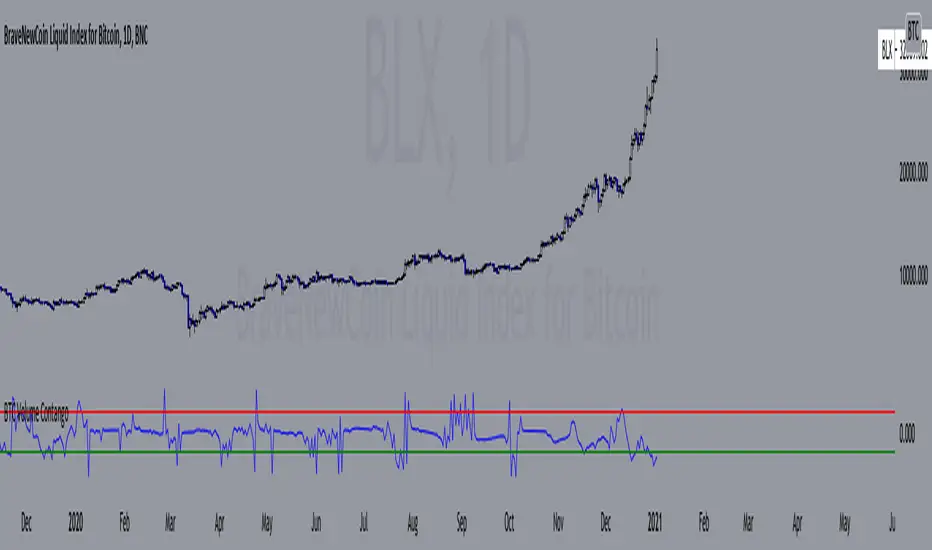
This is a script that shows the contango between spot and futures volumes of Bitcoin to identify overbought and oversold conditions. When a market is in contango, the volume of a futures contract is higher than the spot volume. Conversely, when a market is in backwardation, the volume of the futures contract is lower than the spot volume.
The aggregate daily volumes on top exchanges are taken to obtain Total Spot Volume and Total Futures Volume. The script then plots (Total Futures Volume/Total Spot Volume) - 1 to illustrate the percent difference (contango) between spot and futures volumes of Bitcoin. This data by itself is useful, but because aggregate futures volumes are so much larger than spot volumes, no negative values are produced. To correct for this, the Z-score of contango is taken. The Z-score (z) of a data item x measures the distance (in standard deviations StdDev) and direction of the item from its mean (U):
Z-score = (x - U) / StDev
A value of zero indicates that the data item x is equal to the mean U, while positive or negative values show that the data item is above or below the mean (x Values of +2 and -2 show that the data item is two standard deviations above or below the chosen mean, respectively, and over 95.5% of all data items are contained within these two horizontal references). We substitute x with volume contango C, the mean U with simple moving average ( SMA ) of n periods (50), and StdDev with the standard deviation of closing contango for n periods (50), so the above formula becomes: Z-score = (C - SMA (50)) / StdDev(C,50).
When in contango, Bitcoin may be overbought.
When in backwardation, Bitcoin may be oversold.
The current bar calculation will always look incorrect due to TV plotting the Z-score before the bar closes. อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์

อินดิเคเตอร์